There’s more to this woeful fire insurance story. Here’s how homeowners can be proactive.
Good afternoon.
Those of a certain age will remember Paul Harvey: “And that’s the rest of the story.” I think of Harvey every time I, Pam Marino, have a story so packed full of important information I can’t fit it into a few columns of print. The story I wrote on skyrocketing fire insurance for this week’s paper is one such story.
The story was about the residents of Mountain Shadows Townhomes in Monterey’s Skyline Forest neighborhood, dropped by their insurance company thanks to being located on a map outlining high-risk fire zones. They scrambled to find new insurance, and went from paying $22,000 a year to $250,000 a year for fire insurance.
“We are in an insurance crisis in the State of California,” insurance broker Eileen Topete, CEO of Wright & Kimbrough, told me.
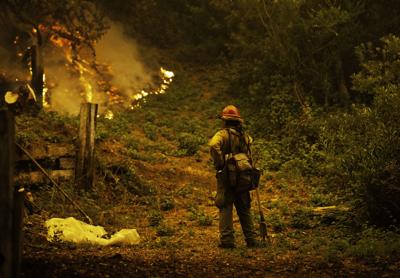
It’s the worst situation she’s seen in 40 years. Dozens of companies have stopped writing new policies altogether. The spiraling costs of climate change-fueled wildfires and other disasters are making it near impossible for companies to make money in the state.
Topete shared with me a lot of very good information for homeowners who will soon find themselves in the same situation as residents of Mountain Shadows. I was able to squeeze in a couple of her tips for homeowners in the story, but here’s some more of her sage advice, based on her vast experience and knowledge of California’s insurance industry.
As a homeowner, you have to be proactive, Topete says. If you receive a letter stating your insurance company is not renewing your policy, call your agent and let them know of any fire hardening projects you’ve done, like a new fire-resistant roof, for example, and see if that makes a difference. (Although Topete says it probably won’t, try anyway.)
If the company still won’t renew your policy, immediately ask your agent to apply for insurance through the California FAIR Plan, a syndicated fire insurance pool composed of all insurers licensed to write property policies in the state, or find an agent who will apply for you. (And check the date of the letter—by law companies have to give you 75-days notice. If it’s less than 75 days, you are entitled to an extension.)
Time is of the essence when applying to the FAIR Plan. The agency is inundated with applications, about 1,000 a day currently, Topete says. It could take a couple of months to get quotes.
Once you’ve secured insurance, Topete advises people to check back with their agent every few months and ask if any new options have developed that might provide you with a less expensive alternative.
If your policy is renewed and the premium is a lot higher than before, pay it, Topete advises. You’ll probably have to go through the FAIR Plan and it’s unlikely you’ll find anything less expensive. You can ask your agent if you can choose a higher deductible and see if that decreases your premium.
Topete says she’s heard of people who have opted to go without insurance—they paid cash for their home or they’ve paid it off and are no longer required to have insurance as part of a mortgage—and it makes her shudder. They could wind up without an ability to rebuild.
How we got into this crisis and how we’ll get out of it—that’s even more “rest of the story” I will focus on in another article. Feel free to share with me your own fire insurance experience, or renter’s insurance issues related to fire risk, if you’re a renter.

(0) comments
Welcome to the discussion.
Log In
Keep it Clean. Please avoid obscene, vulgar, lewd, racist or sexually-oriented language.
PLEASE TURN OFF YOUR CAPS LOCK.
Don't Threaten. Threats of harming another person will not be tolerated.
Be Truthful. Don't knowingly lie about anyone or anything.
Be Nice. No racism, sexism or any sort of -ism that is degrading to another person.
Be Proactive. Use the 'Report' link on each comment to let us know of abusive posts.
Share with Us. We'd love to hear eyewitness accounts, the history behind an article.